Universal Scrap Metals Newsletter — November 2026 

November market conditions strengthened across much of the scrap industry, with tighter supply, improving mill demand, and stronger steel pricing supporting both ferrous and nonferrous markets. Entering the final months of the year, domestic steel mills continued to maintain healthy order books while many planned maintenance outages concluded, allowing production levels and scrap purchasing activity to increase. Several market indicators pointed to stronger pricing momentum compared to the relatively stable conditions experienced during the spring and summer months.

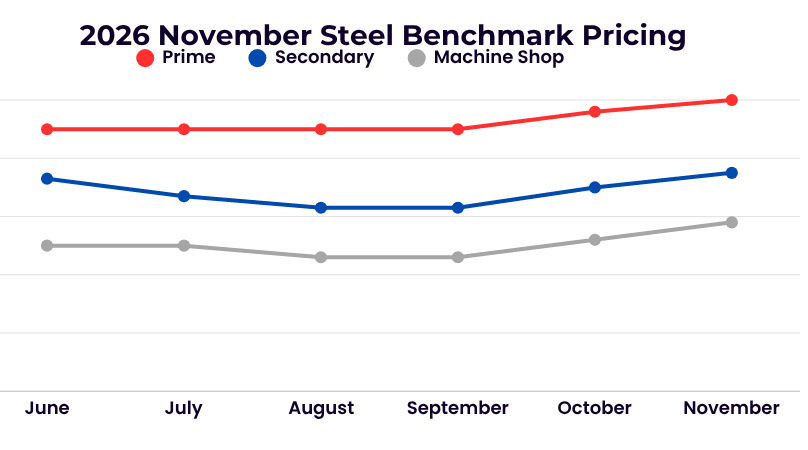
Steel: Ferrous scrap prices moved higher across most grades during November. Improving mill demand, below-average scrap inventories, and slower inbound flows contributed to tighter market conditions. Prime grades, including busheling and bundles, remained well supported by strong steel production and healthy flat-rolled steel pricing. Obsolete grades such as shredded scrap and heavy melt saw some of the strongest gains as export activity improved and seasonal weather conditions began to tighten supply. Industry surveys indicated that many market participants expected further upward momentum, supported by strong demand and lean inventories throughout the supply chain.  

Copper prices experienced significant volatility but continued to trade near historic highs. Supply concerns, strengthening infrastructure investment, electrification projects, and long-term demand from data centers and power infrastructure continue to support copper fundamentals. Despite periodic corrections, copper scrap values remain elevated relative to historical levels and continue to provide attractive returns for suppliers.  

Aluminum markets remained relatively stable throughout November. Primary aluminum prices softened slightly during the first half of the month, but secondary aluminum demand remained healthy. Used Beverage Can (UBC) markets continued to perform well compared to historical norms, supported by strong recycling demand and can-sheet production. Broader aluminum scrap values remained supported by steady demand from packaging, transportation, and construction sectors, although pricing gains were more modest than those seen in copper.  

LME Nickel remains stable with limited pricing pressure in either direction, while stainless demand softens heading into year-end. 304 and 316 scrap remain flat, as do Chrome stainless grades despite stronger iron values. Nickel stability is expected through year-end, although developments in Indonesia, the Philippines, or China could quickly shift market sentiment. 

High-temperature alloys remain mixed, with select grades benefiting from stronger demand while others await mill direction. Titanium pricing remains steady, with meaningful relief not expected until Q4 2027. 

Tool Steel and High-Speed Steel remain resilient despite weakness in Tungsten and Cobalt. Carbide and Tungsten alloys are holding for now, although near-term price erosion remains possible. Overall, mill purchasing appetite and year-end discounting continue to dictate Stainless and Alloy pricing. Despite optimism for a Q1 2027 recovery, subdued mill demand and uncertainty surrounding Nickel supply remain key market concerns. 

Looking ahead, market fundamentals remain constructive as the industry approaches year-end. Ferrous scrap pricing is expected to remain supported by tighter supply, strong mill demand, and healthy steel pricing. Copper is likely to continue driving nonferrous market sentiment, with inventories, trade policy, and infrastructure spending remaining key variables. Aluminum and brass markets should continue benefiting from stable industrial demand and favorable recycling economics, although seasonal weather and holiday-related slowdowns may result in periods of reduced activity.  

 Universal Scrap Metals Newsletter — October 2026 

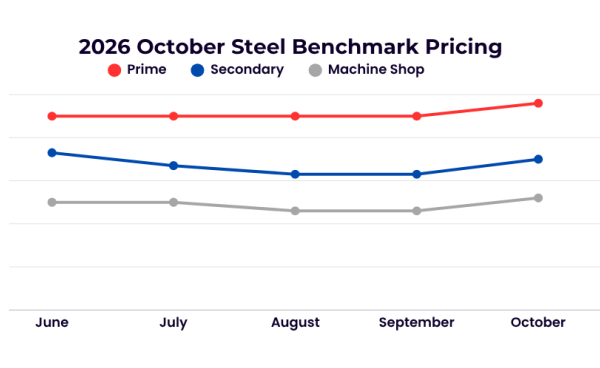
October market conditions have strengthened compared to the late summer months, with improving sentiment across both ferrous and nonferrous markets. Tighter scrap availability, improving export demand, and healthy steel mill order books have provided support for higher pricing, particularly in the ferrous sector. Market participants generally entered October with a more positive outlook, expecting stronger demand and below-average inventories to support pricing through the beginning of the fourth quarter.

In the ferrous market, scrap prices moved modestly higher during October. Market sentiment improved as tightening feedstock, stronger export activity, and healthy mill demand provided upward momentum after several months of largely sideways trading. Prime grades, including busheling, experienced some of the strongest support, while obsolete grades also benefited from lower scrap generation and lean yard inventories. Although scheduled mill maintenance outages continue to temper demand in certain regions, expectations remain favorable heading into the balance of the fourth quarter.  

Steel production remains supportive of scrap consumption despite periodic outages. Market surveys indicate that demand is stable to improving, with many participants reporting stronger business conditions than seen earlier in the year. Tight inventory levels and higher transportation costs have also contributed to firmer ferrous pricing.  

Nonferrous markets remained volatile but generally strong during October. Copper prices continued to trade near historic highs despite periodic profit-taking and market corrections. Supply concerns, ongoing infrastructure spending, data center expansion, and continued electrification projects are providing long-term support for copper demand. While some regional scrap markets experienced short-term fluctuations, overall copper values remain exceptionally strong compared to historical levels.  

Copper continues to be driven by the ongoing pricing disconnect between U.S. COMEX copper and global LME copper markets. Tariff-related arbitrage activity has encouraged large volumes of copper to move into the United States, supporting domestic pricing and keeping scrap values elevated. While inventories have improved from the extreme tightness seen earlier this year, copper remains highly sensitive to supply disruptions, trade policy developments, and global infrastructure demand. As a result, copper scrap prices continue to trade at historically strong levels despite short-term volatility.  

Aluminum markets softened slightly during the first half of October. Several aluminum scrap grades experienced modest declines as secondary consumers adjusted purchasing activity and primary aluminum markets consolidated recent gains. Despite these short-term declines, aluminum fundamentals remain healthy, supported by strong demand from packaging, transportation, and construction sectors. Used Beverage Cans (UBCs) continue to be one of the strongest-performing aluminum scrap categories, supported by robust recycling demand and increasingly tight feedstock supplies.  

Brass markets remained relatively stable throughout October. Elevated copper values continued to provide support for red brass and yellow brass pricing, while demand from foundries and industrial consumers remained steady. Although brass pricing has not experienced the same volatility as copper, values continue to track favorably compared with historical averages due to the strength of the underlying copper market.  

LME Nickel remained relatively stable following its recent decline, with Canadian Thanksgiving limiting trading activity and continued uncertainty surrounding Indonesian supply targets. 304 and 316 stainless grades held flat, though modest year-end reductions remain possible as mills scale back purchases and inventories. Chrome stainless grades should remain firm, supported by improving steel market conditions. 

High-temperature alloys remain subdued amid weakening demand and limited nickel support, with further reductions anticipated through year-end. 

Titanium pricing remains flat despite domestic scrap oversupply, while production backlogs persist due to delivery delays. 

Tool Steel and High-Speed Steel face downward pressure from softer cobalt prices, although molybdenum remains supportive. 

Carbide and tungsten alloys saw brief relief following U.S. critical-materials export restrictions, but weakening European markets have since prompted modest price reductions. 

Looking ahead, fourth-quarter market conditions appear constructive. Ferrous scrap pricing is expected to remain supported by tightening supply, healthy mill order books, and improving export demand. Copper is likely to remain the primary driver within nonferrous markets, with trade policy, inventories, and infrastructure spending continuing to influence price direction. Aluminum and brass should continue to benefit from stable industrial demand, although seasonal factors may contribute to periodic volatility as the year draws to a close.  


 Market Update — September 2026

Good afternoon,

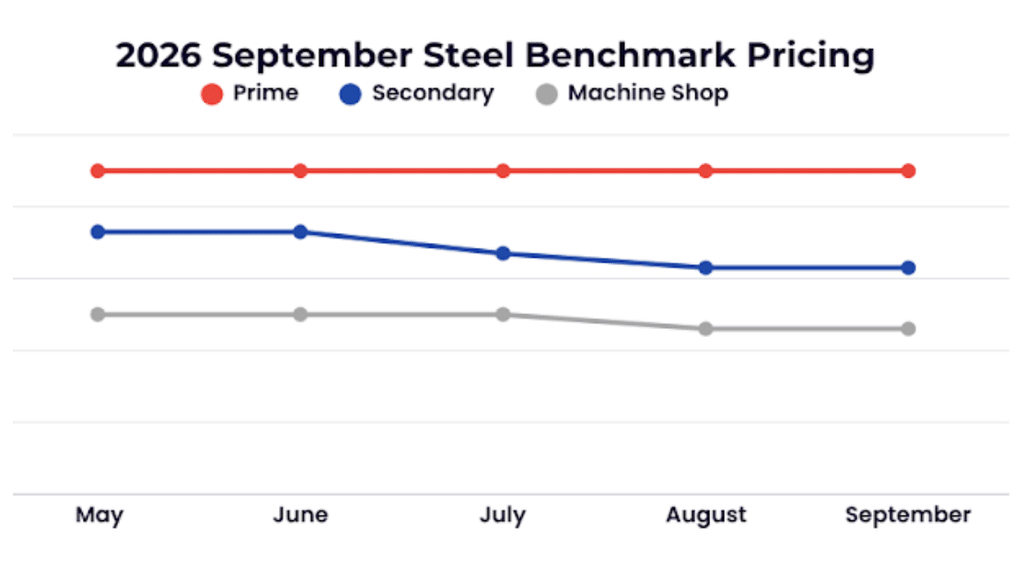
September market conditions remain largely balanced, with both buyers and sellers signaling a neutral outlook following modest softness during August. Inventory levels at steel mills remain near historical averages, and most market participants expect limited movement in either direction during the month. Higher energy costs, seasonal maintenance outages, and stable scrap flows continue to influence market behavior, but no single factor has emerged as a dominant driver. Overall sentiment points toward a sideways market with relatively stable pricing across most scrap categories. 

Steel: In the ferrous market, steel scrap prices have remained generally unchanged as mills balance steady production with planned maintenance outages scheduled throughout September and October. While more than a dozen outage events are expected to temporarily reduce regional demand, tightening scrap flows and reduced feedstock generation have helped offset some of the downward pressure. Prime grades such as busheling continue to be supported by strong finished steel pricing, while obsolete grades remain under pressure due to adequate supply and lingering shredded inventory. Despite these challenges, most forecasts call for ferrous pricing to remain largely sideways during September.

Copper: The copper market continues to be heavily influenced by the pricing gap between U.S. COMEX copper and global LME copper. Ongoing tariff-related arbitrage has encouraged large volumes of copper to move into the United States, supporting domestic prices while reducing available inventories in other regions. This dynamic helped push copper to new record highs in early September, with both COMEX and LME prices reaching unprecedented levels. While recent inventory replenishment has eased some immediate supply concerns, copper remains highly sensitive to policy developments, global inventories, and industrial demand.

Aluminum: Aluminum markets showed modest improvement during the first week of September. Several mill aluminum scrap grades, including 3003, 5052, 6063 Extrusions and UBCs posted gains while secondary aluminum demand recently declined. Although UBC pricing continues to experience periodic volatility, recycled aluminum demand remains supported by can sheet production and broader sustainability initiatives driving closed-loop recycling programs. Overall, aluminum fundamentals remain constructive despite seasonal fluctuations in supply.

Brass: Brass markets have remained relatively stable throughout September. Supported by elevated copper values, brass pricing continues to benefit from healthy demand from foundries and industrial consumers. While brass experienced some weakness during the early September correction in copper markets, values generally remain firm compared to long-term averages. Market fundamentals suggest stable demand and balanced supply conditions heading into the fourth quarter.

Stainless and Alloys: LME Nickel volatility remains tight, with pricing holding within a subdued 30-day range. Demand and the pricing outlook remain stable, with no signs of a summer slowdown. Ferrous values continue to hold, supporting steady Chrome Stainless grades.

High-Temperature Alloys remain aligned with Nickel, although some market participants are applying modest downward pricing pressure.

Titanium prime grades are slightly lower, while Ferro Titanium remains steady.

Tool Steel and High-Speed Steel have seen modest declines, driven by continued weakness in Tungsten. Carbide and Tungsten Alloys continue to correct as consumers and traders gain greater clarity following the implementation of export restrictions.

Looking ahead, market conditions appear likely to remain stable through the beginning of the fourth quarter. Ferrous pricing is expected to remain rangebound as mills manage maintenance schedules and inventory levels. Copper will continue to be the primary driver of nonferrous market sentiment, with tariff policy, global inventories, and arbitrage activity remaining key factors to watch. Aluminum and brass markets should continue to benefit from steady industrial demand and favorable recycling economics, although near-term price movements will remain tied to broader commodity trends.


 Market Update — August 2026

August market conditions have remained largely stable, with balanced supply and demand limiting significant price movement across most scrap grades. Most consumers continue to point to a relatively quiet summer trading environment, as mill outages, seasonal slowdowns, and weaker export activity temper demand while scrap availability remains generally adequate. Inventories at domestic mills remain near historical averages, contributing to a market that is stable but lacking a strong directional catalyst.

Steel: 

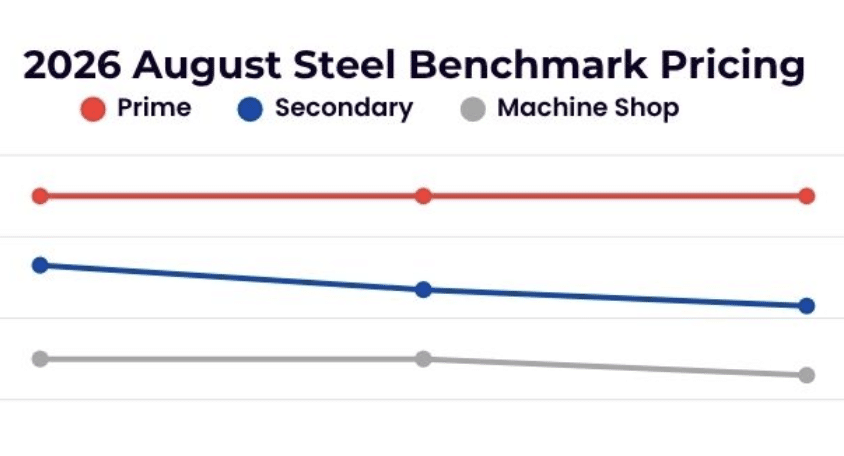
In the ferrous market, prime steel scrap prices remain unchanged from July levels, while cut grades declined again this month. Strong domestic steel production continues to support consumption, with U.S. mills producing approximately 1.87 million net tons of raw steel in the week ending August 1 and operating at an 81.0% utilization rate. While prime grades remain relatively well supported by strong finished steel pricing and solid mill order books, buyers generally continue to pursue a cautious purchasing strategy.

Copper: 

Copper remains one of the strongest-performing commodities in the market. U.S. COMEX copper prices reached new record highs in early August as continued tariff uncertainty and supply concerns encouraged additional metal to move into the United States. The pricing gap between COMEX and the London Metal Exchange (LME) remains elevated, creating arbitrage opportunities that support domestic pricing.

Aluminum:

Aluminum markets improved modestly during August, with most scrap grades recording gains during the first week of trading. Demand for secondary aluminum remains stable, supported by can sheet, automotive, and industrial applications. Used Beverage Cans (UBCs) continued to perform well, posting gains from July levels and maintaining one of the stronger trends within the aluminum complex. National pricing indicators show UBC values trending higher than earlier in the summer, supported by steady consumption and ongoing demand for recycled aluminum feedstock.

Brass:

The brass market also strengthened during August, benefiting directly from the continued rise in copper prices. Brass scrap values posted modest week-over-week gains as foundries and consumers maintained steady purchasing activity. While increases have been measured, the overall market remains firm, particularly for red brass and higher-copper-content grades.
Stainless and Alloys: 

LME Nickel remains in a tight trading range with a slight upward bias. Demand and pricing are stable, despite the typical summer slowdown. 304 and 316 stainless values continue to hold, while chrome-bearing grades may see a modest correction.

High-Temperature Alloys remain steady on moderate demand, though pricing has yet to return to year-to-date highs.

Titanium is relatively flat with a moderately bullish outlook, particularly for clean aerospace grades.

Tool Steel and High-Speed Steel remain somewhat volatile, especially Moly and Tungsten bearing grades. T-Series grades face greater downside risk as the underlying market softens.

Carbide and Tungsten Alloys continue to face headwinds, with softer demand and customers drawing down existing inventories rather than rebuilding.

Looking ahead, market fundamentals suggest continued stability through the remainder of the summer. Ferrous pricing is expected to remain rangebound as mills balance adequate scrap inventories with steady steel production. Copper is likely to remain the key driver within the nonferrous sector, supported by strong COMEX pricing and ongoing supply concerns. Aluminum and brass markets should continue to benefit from supportive underlying commodity prices and consistent industrial demand, although seasonal factors may limit significant upside in the near term.


 Market Update – July 2026

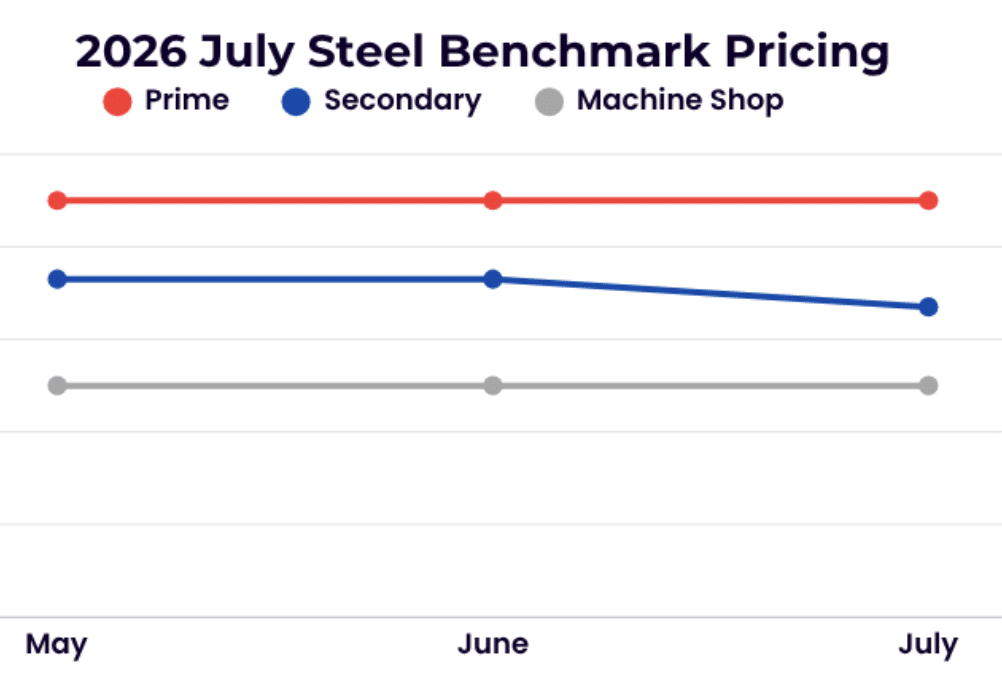
July market conditions remained generally stable, although sentiment softened across parts of the ferrous sector as seasonal mill outages, extreme heat, and summer operating schedules tempered demand expectations. Scrap availability remained adequate in most regions, and inventory levels were reported near historical averages, resulting in a balanced market without a clear catalyst for significant price movement. While buyers adopted a cautious approach, overall pricing remained relatively steady across most grades. 

Steel

In the ferrous market, steel scrap prices remained largely unchanged through the first half of July as domestic mills maintained consistent purchasing patterns and continued operating at healthy utilization rates. U.S. raw steel production remained strong, with mills producing approximately 1.86 million net tons per week and operating above 80% capacity utilization. Year-to-date steel output remained roughly 6% above 2025 levels, supporting ongoing scrap consumption. However, weaker export demand, particularly from Turkey (the world’s largest scrap importer) continued to limit upside potential for obsolete grades such as shredded scrap and HMS. 

Copper

Nonferrous markets were more constructive during July. Following June’s surge to record-high copper prices and the subsequent correction of approximately 10% later in the month, copper scrap prices stabilized and posted modest gains across most major grades in July. Market support continued to come from steady industrial demand, ongoing infrastructure investment, and strength in the underlying copper market. While month-to-date gains have been relatively modest, copper prices remain at historically elevated levels compared to long-term averages, providing continued support for copper scrap values.

Aluminum

Aluminum markets are starting to rebound somewhat during July after a mixed performance through much of the second quarter. Some secondary aluminum scrap grades posted gains, including Used Beverage Can (UBC) during the first half of the month as secondary aluminum demand improved experienced week-over-week gains. Despite these improvements, aluminum pricing remains dependent on broader primary aluminum trends and seasonal scrap flows.

Brass

Some Brass markets also moved higher during July, benefiting from copper’s strength. Both red brass and yellow brass prices recorded modest gains, reflecting stable demand from foundries and industrial consumers. Price increases remained measured, but the market continued to trend positively compared with the relatively flat conditions seen earlier in the summer. 

Stainless Steel & Alloy

LME nickel traded approximately $0.60/lb below the June average, largely driven by uncertainty surrounding Indonesian export policies and supplier agreements. A softer market is anticipated over the next six months as participants monitor global demand trends and supply chain developments. 304 stainless pricing softened modestly, while 316 grades remained firm, supported by steady demand and molybdenum support. Chrome-bearing stainless grades have also held pricing for the time being.

Despite stable demand, high-temperature alloy pricing moved lower in line with nickel’s decline. Titanium pricing remained relatively steady, with increased market participation potentially supporting modest strengthening ahead. Tool steel and high-speed steel markets edged lower due to softer demand and seasonal summer slowdowns. The tungsten alloy market also weakened from the prior month as speculative inventories re-entered the market, pressuring demand.

Looking ahead, the market enters the latter part of summer with generally balanced fundamentals. Ferrous pricing is expected to remain stable barring significant changes in export activity or domestic steel production. Copper appears poised to remain the strongest nonferrous performer, supported by elevated COMEX pricing and ongoing infrastructure and electrification demand. Aluminum and brass markets are expected to continue tracking broader base metal trends while remaining sensitive to regional supply and demand conditions.